BILL AP & AR Business Payments
Bill.com Inc.BusinessVerified
- 1.54K Reviews
- 4.3
- Downloads
- 500,000+
- Price
- Free
Screenshots
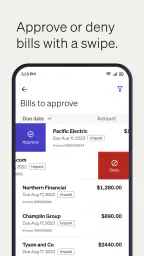
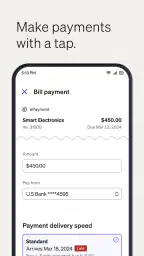
 Analysis by Appwesome
When a small business is juggling supplier invoices, customer payments, and a crowded email inbox, the hardest part is often not sending money. It is keeping the whole payment trail understandable. BILL AP & AR Business Payments is built for that gap. I see it as a business payment app from Bill.com Inc. that brings accounts payable and accounts receivable into one mobile workflow, rather than treating paying bills and getting paid as completely separate jobs.
I approached it as I would any work app I might recommend to a friend: not by asking whether it sounds useful, but by asking where it fits in a normal week. The answer is fairly clear. It is most appealing when a business already has recurring invoices, several people involved in approvals or payment follow-up, and a need to work away from a desktop. It is less convincing for someone who only pays a handful of bills or wants a full accounting system inside a phone.
From an incoming invoice to a completed payment
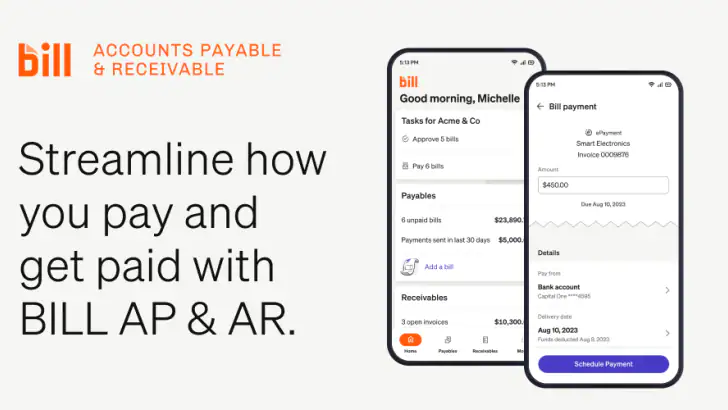
I use this section to trace how a bill moves from arrival to payment, while keeping the decision points visible rather than treating a quick tap as the whole job. A useful habit is to check who owns the next action before anything moves forward; that small pause can prevent an invoice from being mistaken for an approved expense.
The starting condition: payment work is scattered
A realistic example is a small design studio that receives an invoice from a freelance editor while its owner is traveling. The invoice may arrive by email, the owner may need to check whether the work was completed, and someone else may eventually need to release the payment. At the same time, a client could be late paying the studio. These are two different directions of money, but they create the same practical problem: somebody needs a reliable view of what is waiting, what is approved, and what still needs attention.
This is where the app makes sense. Its focus is not general office administration; it is the movement of bills and business payments. Instead of opening a banking app for one task, an accounting tool for another, and an email thread for the explanation, I would use BILL AP & AR as the payment-focused workspace. That narrower purpose is a strength because it keeps the main question in view: what needs to be paid, and what needs to be collected?
The app is free, carries an Everyone content rating, and has been available since December 16, 2015. Its position in the Business category is reflected in the way it treats payments as a shared work process rather than a personal money-transfer tool. I would still expect a business to keep its accounting records and banking arrangements organized elsewhere when necessary, but the app can serve as the operational layer between an obligation and its outcome.
Step one: deciding what deserves attention
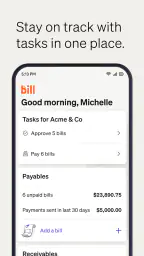
The first useful habit is to avoid treating every invoice as equally urgent. A bill with a near deadline, a payment that requires a colleague’s review, and a customer receivable that has been waiting all need different actions. A mobile payment app is valuable when it helps me make that distinction quickly instead of forcing me to reconstruct the situation from messages and attachments.
Other Stories to Read



For a business owner, I would begin by reviewing the items that need a decision rather than trying to process everything in one sitting. That means checking the invoice context, confirming that the expense belongs to the business, and identifying whether another person should be involved before money moves. This is one of the less obvious benefits of using a dedicated AP and AR tool: the review step becomes part of the routine, not an afterthought after a payment has already been made.
On the receivables side, the same discipline helps prevent wishful bookkeeping. A customer saying “we will pay soon” is not the same as money received. Keeping the collection task visible gives me a reason to follow up while the invoice is still relevant, rather than waiting until cash flow becomes uncomfortable. The app is therefore more useful for businesses that want a repeatable process than for people who only need an occasional transfer.
Step two: checking the details before approval
Mobile convenience can create a dangerous temptation: approving something simply because it is easy to tap. I would use the phone for review, but I would not skip the basic checks. The supplier, amount, purpose, and timing should make sense before I move an item forward. If the invoice relates to a project, I would also compare it with the project’s own records, because a payment app cannot replace the person who knows whether the work was actually delivered.
This is an important trade-off. A phone is excellent for catching up between meetings, but a large screen may be better when an invoice has a long description, several supporting documents, or a complicated split. I would not make the app my only review environment for high-value or unusual expenses. Its role is strongest when the information is already understandable and the user needs to approve, monitor, or follow up without being tied to a desk.
For accounts receivable, checking details means making sure the customer and invoice are correctly matched before sending a request or recording progress. A small mistake at this stage can make a later conversation awkward. My practical advice is to use the app to keep the workflow moving, but pause whenever the payment depends on a contract interpretation, a disputed charge, or a change in scope.
Step three: making the handoff clear
Payment work rarely belongs to one person from beginning to end. An employee may enter an invoice, a manager may approve it, and an owner may want visibility over cash leaving the business. On the incoming side, one person may issue the invoice while another watches for the payment. The value of BILL AP & AR is tied to these handoffs: each person should know whether they are expected to review, approve, pay, or follow up.
I find this more useful than a simple banking app because a bank account usually shows the transaction after it happens. It does not naturally explain why the transaction is waiting or who needs to act next. Conversely, a spreadsheet can record status, but it depends on everyone updating it consistently. A payment workflow app sits between those extremes. It offers a more purposeful place to manage the work, while still requiring the team to agree on its habits.
A good handoff is not just a notification. It includes enough context for the next person to make a decision without starting a new investigation. If I were setting this up for a small team, I would agree on a simple rule: no item should be passed along without a clear reason for the next step. That might be approval, payment scheduling, customer follow-up, or a request for clarification. This small discipline prevents the app from becoming another inbox.
Step four: following payment through to the result
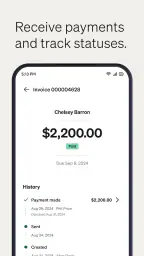
The outcome I want from an accounts payable workflow is not merely that money leaves the business. I want the bill to reach a completed state that the team can understand later. That matters when checking cash flow, answering a supplier’s question, or preparing records for reconciliation. On the accounts receivable side, the result is not merely sending an invoice; it is knowing whether the customer has paid and whether somebody needs to act again.
This is where the app’s combined AP and AR focus can be practical. Money going out and money coming in affect the same operating reality, especially for a small company. Looking at both sides encourages better timing decisions. For example, a business might delay a non-urgent outgoing payment until it has a clearer view of expected customer receipts, while still respecting agreed terms. The app does not make that decision for me, but it can make the information easier to organize.
I would also use the completed workflow as a learning tool. If a particular supplier invoice repeatedly needs clarification, the problem may be the purchasing process rather than the payment app. If customer follow-ups are always late, the business may need a regular review routine. The best result is therefore not just fewer clicks; it is a clearer pattern of responsibility across the company.
Where the workflow breaks
The first point of friction is complexity. Businesses with unusual approval structures, many currencies, specialized accounting requirements, or heavily customized procurement rules may outgrow a mobile-first payment workflow. The app can help organize payment activity, but I would not assume it replaces every financial control a larger organization needs.
The second is human behavior. If one person keeps approving items without checking them, or if another person treats the app as a storage bin for unresolved questions, the workflow will still fail. No payment tool can repair unclear authority. Before adopting it, I would decide who may approve, who may release a payment, who handles customer follow-up, and how exceptions are documented.
The third is the difference between monitoring and doing deep financial work. A phone is convenient for a quick review, but detailed reconciliation, reporting, and investigation can be more comfortable in a broader accounting environment. If the main requirement is payroll, inventory, tax preparation, or full bookkeeping, I would choose a dedicated system for that job and consider BILL AP & AR as a focused companion rather than the center of everything.
There is also a practical adoption question. A tool that serves both AP and AR can be valuable, but a business that only needs one narrow task may find the combined scope unnecessary. A freelancer with very few expenses and one or two customers might prefer direct bank tools and a simple document system. The app becomes more compelling as payment volume, handoffs, and follow-up responsibilities increase.
How it compares with familiar alternatives
The usual alternative is online banking. Banking apps are familiar and useful for seeing balances or making transactions, but they generally begin at the point where money is ready to move. BILL AP & AR is better suited to the work before and around that moment: reviewing obligations, coordinating people, and keeping incoming and outgoing payment tasks in one business context.
Another alternative is a spreadsheet. A spreadsheet is flexible and inexpensive, and I would still use one for custom analysis when needed. Its weakness is that status depends on manual discipline. It can tell me that an invoice is “pending,” but it may not make the next handoff obvious. A dedicated workflow feels more appropriate when several people need a shared process rather than a private list.
Accounting software is the more complete alternative. It can be the better choice when the business needs broad financial records, reporting, and reconciliation in one place. BILL AP & AR has a more focused appeal: it addresses the practical movement of bills and receivables without asking the user to turn every payment task into a full accounting exercise. I would choose between them based on whether payment coordination or comprehensive financial management is the primary problem.
Who will get the most from it
I would recommend this app to a small business owner who approves payments while away from the office, a team that needs clearer responsibility around supplier bills, or a service business that wants to keep customer collections from disappearing into email. It is also a reasonable fit for someone who wants one mobile place to check both payables and receivables during a busy day.
The strongest use case is a business with enough activity to create friction, but not so much complexity that every payment needs a specialized enterprise process. In that middle ground, the app can reduce the mental load of remembering which invoice is waiting on whom. It gives the owner a more deliberate workflow than a bank transaction list and less manual maintenance than a spreadsheet.
I would be more cautious for a person who rarely sends or receives business payments, a company with strict finance controls that require a highly tailored system, or anyone expecting a complete accounting replacement. Those users may be better served by a banking app, a spreadsheet, or a full accounting platform depending on the problem they are actually trying to solve.
What the current app profile suggests
The app has a 4.3 average from around 7,500 ratings and has passed 500,000 installs, which tells me it has reached a meaningful audience without making popularity the only reason to use it. The current version is 3.7.171, and it supports iOS 9 or later. I would check device compatibility before planning a rollout, especially if a team uses older phones.
Those details matter less than the workflow fit, but they help set expectations. This is an established business app rather than a brand-new experiment, and its purpose remains specific: accounts payable and accounts receivable. I would judge it by whether it helps my team move from invoice received or payment expected to a clear next action and a traceable result.
My practical setup advice
If I were introducing it to a business, I would start with one recurring payment routine instead of moving every financial task at once. For example, I might use it first for supplier invoices that regularly require owner approval. After the team understands the handoff, I would add customer payment follow-up. This staged approach makes it easier to identify whether the app is solving a real bottleneck or merely adding another place to look.
I would also create a short internal checklist for every item: confirm the party, confirm the reason, identify the decision-maker, and decide what completion looks like. That checklist is deliberately simple, but it protects against the most common mobile-workflow mistake: confusing speed with accuracy. The app can make action easier; the business still needs a consistent standard for action.
Finally, I would schedule a regular review of unresolved items. A payment tool is most useful when pending work does not become invisible. Looking at the queue at a fixed point in the week can reveal late customer payments, repeated invoice problems, or approvals that are stuck with one person. That is a more advanced use than simply paying a bill from a phone, because it turns the app into a management aid.
My recommendation
After looking at the complete journey, I see BILL AP & AR Business Payments as a focused tool for businesses that need to coordinate money going out and money coming in. Its best quality is not the promise of effortless payments; it is the way a dedicated AP and AR workflow can make responsibilities visible before the transaction happens.
I would recommend it to a growing small business, especially one where the owner, bookkeeper, and staff share payment duties. I would skip it if my needs were limited to occasional transfers or if I required a full accounting environment with extensive customization. For the right workflow, though, the biggest benefit is a clearer handoff from invoice to decision to completed payment.
Bill.com Inc. has made an app that is practical when payment administration is becoming a daily operational problem. My honest view is that it works best when paired with clear team habits and sensible financial checks. Used that way, it can help a business spend less time hunting through messages and more time knowing exactly what needs attention next.
Highlights
- Streamlines invoice creation
- tracking
- and payment management in one place.
- Helps businesses maintain clearer records of accounts payable and receivable.
- Supports faster payment workflows
- reducing manual administrative tasks.
- Useful for monitoring outstanding invoices and improving cash-flow visibility.
- Can make collaboration between finance teams and clients more organized.
Limitations
- May require setup time to match existing accounting processes and payment rules.
- Advanced features may depend on the subscription plan or business account type.
- Users may need training to use all invoicing and reporting tools efficiently.
- Payment availability can vary by country
- currency
- and supported financial providers.
- Businesses should review security and access settings before inviting team members.
Frequently Asked Questions
01What is BILL AP & AR Business Payments used for?
BILL AP & AR Business Payments is designed to help businesses manage accounts payable and accounts receivable from one platform. After reviewing the app, its main purpose is to simplify sending payments, receiving money, organizing invoices, and tracking transaction activity. It is aimed primarily at businesses and finance teams rather than personal users managing occasional household bills.
02Is BILL AP & AR Business Payments suitable for small businesses?
Yes, the app can be useful for small businesses that want to centralize billing and payment tasks without relying entirely on spreadsheets or separate tools. It may help owners, bookkeepers, and finance staff schedule payments, monitor incoming funds, and maintain clearer records. However, suitability depends on your company’s payment volume, accounting workflow, supported payment methods, and any fees associated with the services you plan to use.
03Can I send and receive payments through the app?
BILL AP & AR Business Payments supports business payment workflows for both outgoing and incoming transactions, although the exact options can depend on your account type, region, verification status, and the payment method selected. Before downloading, businesses should confirm whether their preferred bank accounts, cards, vendors, customers, and currencies are supported. Processing times and transaction fees may also vary.
04Is BILL AP & AR Business Payments secure to use?
The application is built for handling sensitive business and payment information, so security features and identity verification are important parts of the experience. Users should still protect their login details, enable available authentication options, and avoid accessing financial accounts on unsecured networks. No payment platform is completely risk-free, so businesses should regularly review account activity, user permissions, and notifications.
05Does BILL AP & AR Business Payments integrate with accounting software?
Integration with accounting software can be one of the app’s most useful features because it may reduce duplicate data entry and help keep invoices, payments, and financial records synchronized. Available integrations and capabilities can differ according to the subscription, country, and accounting platform being used. Before signing up, check the current integration list and verify whether synchronization meets your company’s bookkeeping requirements.


